India’s Insolvency and Bankruptcy Code (IBC), introduced with fanfare in 2016, was hailed as a watershed reform in resolving corporate debt.
But fast forward to 2025, and India’s leading bankers are not just losing money — they’re losing hair.
Frustrated by delayed resolutions, meagre recoveries, and legal gridlocks, finance professionals are raising serious questions:
Has the IBC lived up to its promise? Or is it becoming a cautionary tale?
Let’s dive into the cracks in the current system, real-world implications, and what professionals across finance, law, and business should prepare for next.
🔍 The Root of the Crisis
The IBC was meant to be swift and decisive: resolve insolvency in 180 days, protect creditor rights, and boost India’s investment climate. In theory, perfect. In practice? A different story.
Key pain points:
Delayed resolutions: The average resolution time now exceeds 650 days — far from the 180-day target.
Low recovery rates: Creditors are often recovering less than 30% of their dues.
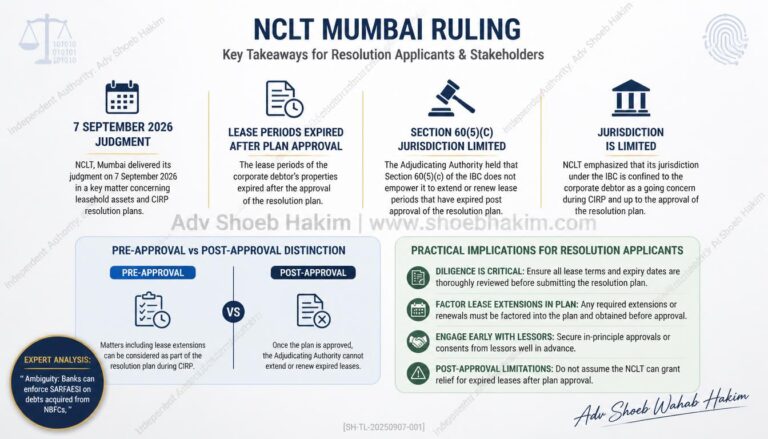
Judicial gridlock: The National Company Law Tribunal (NCLT) is burdened with thousands of unresolved cases.
Backdoor entries: Former promoters are finding ways to re-enter companies via legal loopholes.
These issues are not just operational hiccups—they’re structural barriers that undercut investor confidence and financial discipline.
📉 Real-World Example: The Videocon Debacle
The Videocon Group insolvency case shocked the banking community when creditors accepted a settlement with less than 5% recovery.
With nearly ₹62,000 crore owed to lenders and a paltry ₹2,962 crore paid out, the case highlighted the limitations of the process, especially when assets are difficult to value or contested in court.
📘 A Step-by-Step Breakdown: Where the System Fails
Admission Delays
NCLT’s chronic shortage of members leads to delayed case admissions — sometimes taking over a year to admit insolvency pleas.Resolution Process Bottlenecks
Creditors committees (CoC) lack transparency. There’s no uniform approach to valuations or bidder selection.Judicial Interventions
High Courts and the Supreme Court frequently intervene, creating further uncertainty.Exit and Liquidation Confusion
Liquidation often yields negligible returns. In many cases, assets are sold for scrap.
⚖️ Implications for Professionals
For Bankers:
Stress-testing portfolios is now a must.
Collateral evaluation frameworks need urgent upgrades to reduce future NPAs.
For Legal Teams:
Specialized insolvency litigation skills are in demand.
Due diligence for revival schemes should account for promoter manipulation.
For Investors and Corporate Boards:
Exit strategy planning is essential before entering high-debt sectors.
Legal risk analysis should be factored into business forecasts.
💡 Practical Tips to Navigate the Chaos
✅ Strengthen internal compliance: Monitor borrower conduct even post-loan disbursement.
✅ Prepare for delays: Build delay assumptions into your recovery models.
✅ Engage IBC experts: Have legal and financial consultants on standby for real-time strategy updates.
✅ Monitor IBBI updates: Track regulatory reforms closely; India’s bankruptcy regime is still evolving.
✅ Train cross-functional teams: Finance, compliance, and legal must work in unison.
🚀 Challenges vs Opportunities
Challenges:
Delays and low recoveries are straining India’s credit ecosystem.
Overloaded legal infrastructure undermines the Code’s credibility.
Opportunities:
Upcoming IBC amendments may introduce pre-pack frameworks and faster MSME resolution models.
Legal tech and AI-driven due diligence can plug process gaps.
📌 Key Takeaways
The IBC, once a beacon of hope, is now a work in progress.
Professionals must anticipate delays, legal ambiguity, and financial write-downs.
Specialized expertise, regulatory awareness, and digital solutions will be critical in this new landscape.
✅ Conclusion: Don’t Just Watch — Prepare
India’s insolvency law isn’t broken — but it’s far from fixed. As professionals, the time to adapt is now.
Bankers, lawyers, compliance teams, and business owners must rethink how they handle credit risk, recovery strategy, and legal workflows.
📥 Download our free guide: “10 Questions Every Bank Must Ask Before Filing Under IBC.”
🔗 Stay updated with expert analysis on shoebhakim.com/
📣 Share this article with your network to start the conversation on how to repair — and reinvent — India’s debt recovery system.
#IBCIndia #InsolvencyLaw #BankingCrisis #LegalCompliance #FinanceProfessionals #IndiaNews #LegalInsights IBCIndia #BankingReform #LegalTech IBCIndia #DebtRecovery #BankingReform #LegalProfessionals #FinanceLaw #IndiaBusiness #NCLT #LegalCompliance