Why Adv Shoeb Hakim Considers This Article a Vital Read
Bank closures, though rare, are a pressing concern for depositors. Understanding the steps to secure your money under the Deposit Insurance and Credit Guarantee Corporation (DICGC) Act is vital for ensuring financial safety.
This guide simplifies the process to help you act swiftly in case of a bank shutdown.
What Happens to Your Money When a Bank Closes?

Understanding Bank Closures
When a bank ceases operations due to financial instability or regulatory actions by the Reserve Bank of India (RBI), depositors often worry about their savings. Thankfully, the DICGC Act offers a safety net, ensuring a measure of protection for depositors.
The DICGC Act: A Shield for Depositors
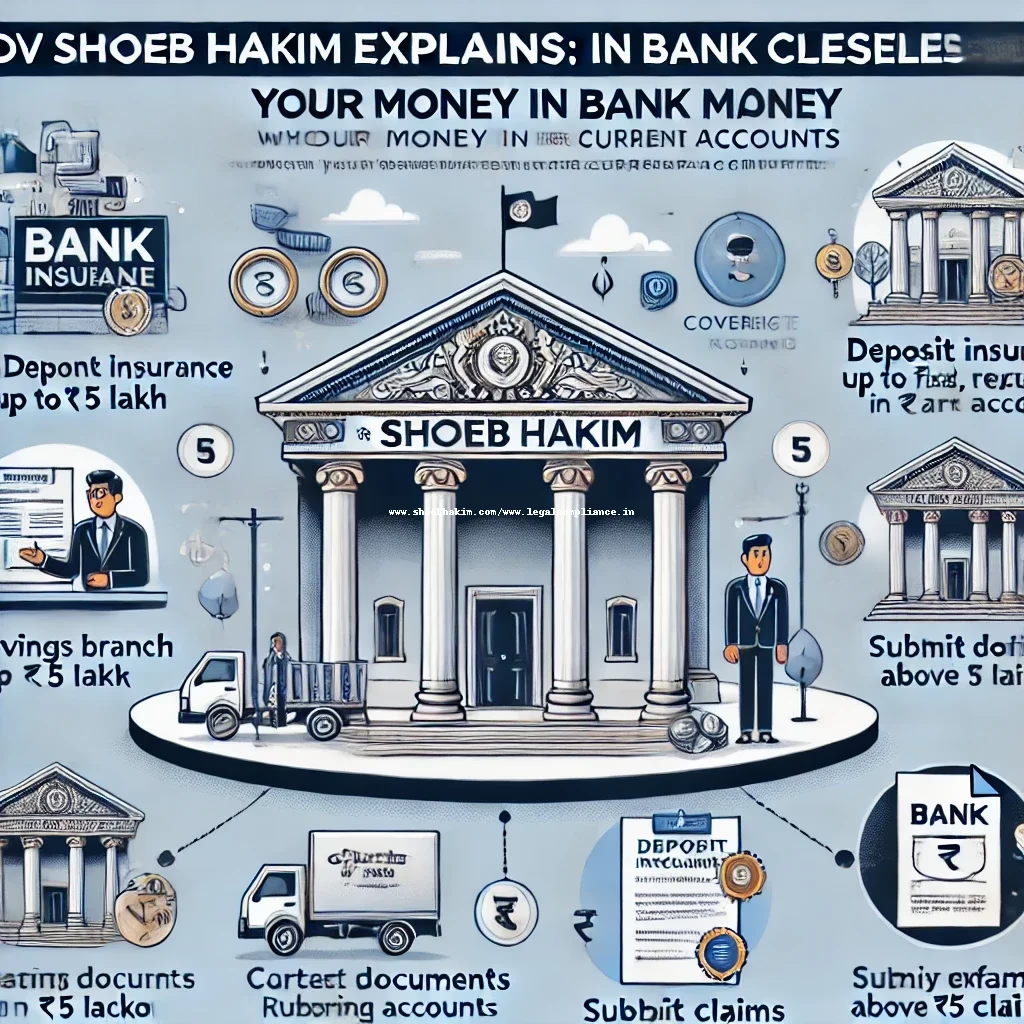
The Deposit Insurance and Credit Guarantee Corporation (DICGC) Act provides insurance coverage of up to ₹5 lakh per depositor per bank. This includes the principal and accrued interest.
Key Features of Deposit Insurance:
- Coverage Limit: Up to ₹5 lakh per depositor per bank (inclusive of interest).
- Eligibility: Applies to savings accounts, fixed deposits, recurring deposits, and current accounts.
- Guarantee: The insured amount is disbursed promptly after the bank’s liquidation.
Steps to Claim Your Money Under the DICGC Act
1. Contact Your Bank Branch
Immediately after the bank’s closure is announced, visit your branch. Bank officials can guide you on:
- Claim procedures.
- Documentation requirements.
2. Gather Required Documents
Prepare the following:
- Proof of Identity: Aadhaar, PAN, or voter ID.
- Account Details: Passbook or account statements.
- Claim Forms: Available from the bank or the DICGC.
3. Submit a Claim
Under Section 16(1) of the DICGC Act, 1961, the claim process involves:
- Banks submitting claims to DICGC on behalf of depositors.
- Verification by DICGC.
- Direct transfer of the insured amount to depositors.
4. Claims for Deposits Above ₹5 Lakh
If your deposits exceed ₹5 lakh:
- File a claim with the liquidator appointed for the bank.
- Participate in the liquidation process to recover the excess amount.
The Role of the DICGC
The DICGC, a subsidiary of the RBI, ensures:
- Safety: Protects depositors up to ₹5 lakh.
- Coverage: Includes commercial banks, regional rural banks, and cooperative banks.
- Efficiency: Facilitates the quick disbursement of insured amounts.
Real-Life Example: PMC Bank Crisis
The collapse of Punjab and Maharashtra Cooperative (PMC) Bank highlighted the importance of the DICGC Act. Thousands of depositors benefitted from the insurance coverage, though recovery of amounts above ₹5 lakh depended on the bank’s liquidation proceedings.
Adv Shoeb Hakim’s Analysis & Conclusions
Understanding the DICGC Act empowers depositors to safeguard their money even during financial crises. Key takeaways include:
- Act Promptly: Begin the claim process immediately after closure announcements.
- Be Prepared: Keep essential documents ready for submission.
- Know Your Rights: Awareness of the DICGC’s provisions ensures you receive what you’re entitled to.
Call to Action: For detailed insights into your rights as a depositor, visit shoebhakim.com.
Quiz: Test Your Knowledge
- What is the maximum amount insured under the DICGC Act?
- a) ₹2 lakh
- b) ₹5 lakh
- c) ₹7 lakh
- Who oversees the DICGC?
- a) SEBI
- b) RBI
- c) Ministry of Finance
Related to This Similar Cases/Articles You Must Read:
#advshoebhakim, #shoebhakim, #advshoaibhakim, #bankclosures, #DICGCAct, #bankliquidation, #RBI, #financialsafety, #depositinsurance, #bankingstudents, #PMCbank, #indianbanking, #safedeposits, #liquidationprocess, #bankingregulations, #insureddeposits, #protectingdeposits, #knowyourrights, #financialawareness
DISCLAIMER:
The content presented in this document is entirely fictional and represents a creative endeavor intended solely for entertainment purposes. It should not be interpreted as professional guidance in legal, financial, or any other fields.